Your Shipment Arrived Crushed. What Declared Value Costs, and What It Actually Buys
A plain reading of the terms on a freight bill: released value by the pound, declared value, carrier-packed versus customer-packed, and what each one commits you to when a box arrives damaged.
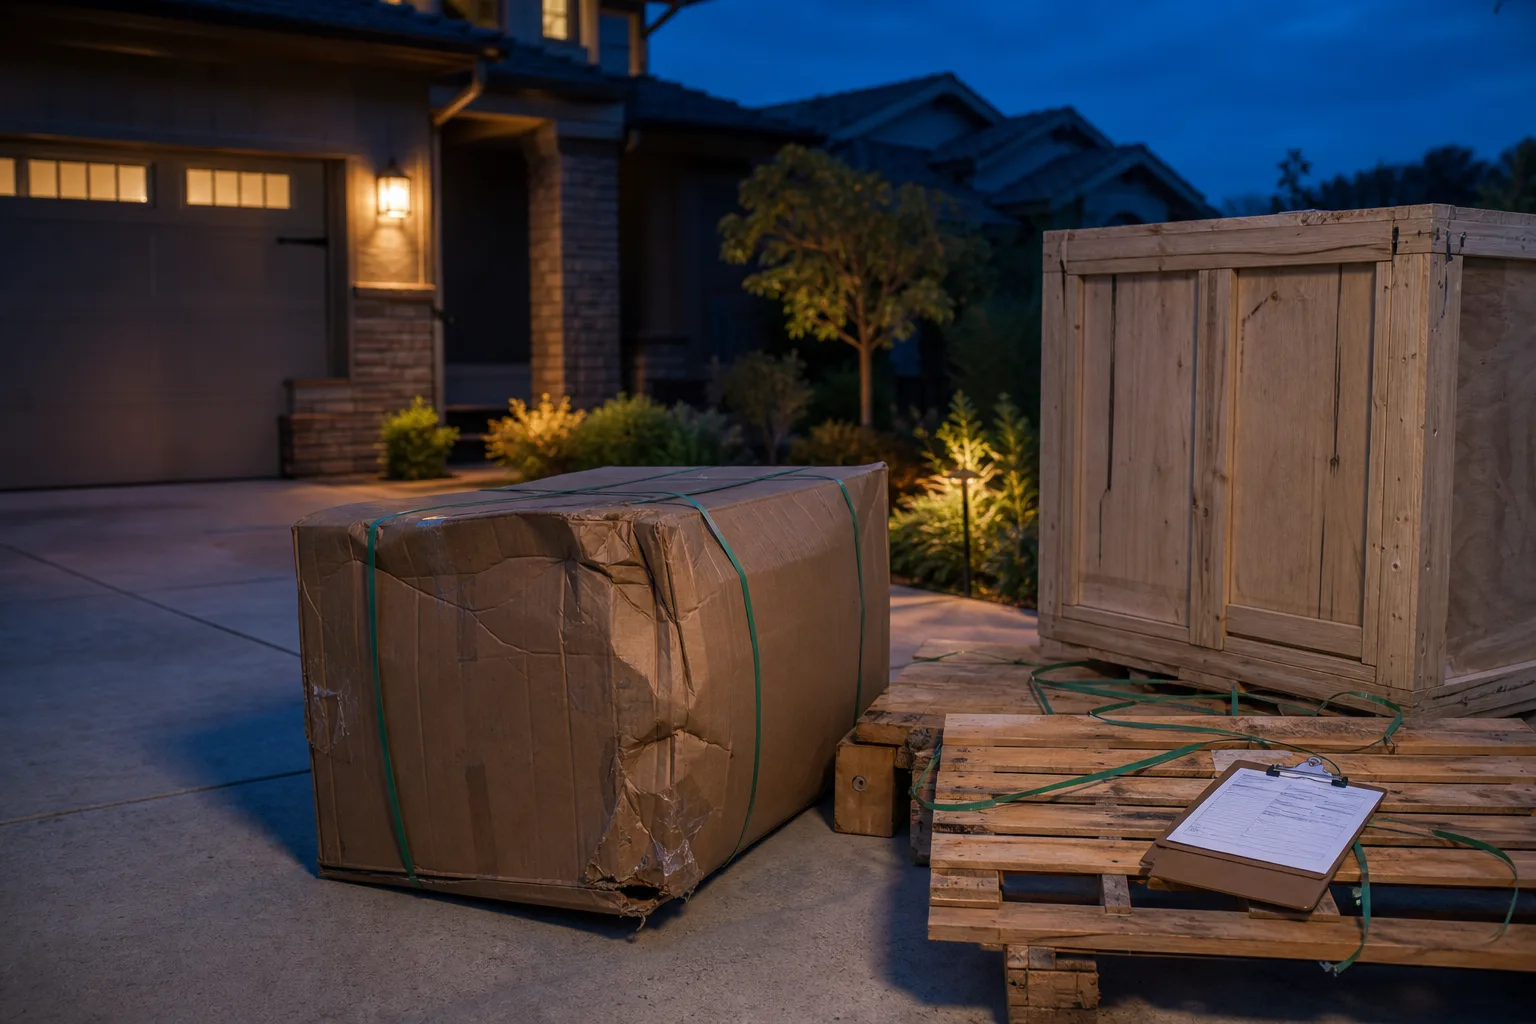
The moment a shipment goes wrong is the moment you discover which words on the paperwork were load-bearing. Most customers read a freight quote as one number, the price to move the thing, and treat everything under it as boilerplate. In practice you bought three separate products: transportation, packing, and liability. Each is priced differently, each can be upgraded or waived, and the third one decides whether a cracked marble table top becomes a two hundred dollar check or a full replacement. Knowing which of the three you skimped on tells you, before you file anything, roughly how the claim will end.
Released value is the default, and it is priced by the pound
Interstate motor carriers move almost everything under a published liability limit called released value, sometimes written as released rates or standard liability. It is measured in dollars per pound per article, not in dollars per item, and the figure sits in the carrier's tariff or in the terms attached to the bill of lading. Common household-goods numbers run around sixty cents a pound, and less-than-truckload freight often sets limits by freight class instead. The arithmetic is unkind to anything light and expensive. A forty pound television at sixty cents a pound is a twenty-four dollar recovery, regardless of what you paid for it.
Released value is not free coverage that came with the shipment. It is the ceiling on what the carrier owes when the carrier is at fault, and it applies whether or not the driver did anything careless. The Federal Motor Carrier Safety Administration oversees interstate motor carriers and the disclosure obligations that come with moving household goods across state lines, which is why the valuation choice usually appears as a box you initial rather than a line buried in fine print. If nobody asked you to initial anything, you are almost certainly at the default, and the default is the cheapest outcome for the carrier.
Declared value, full value protection, and the difference from insurance
The upgrade has several names depending on the trade. Movers sell full value protection; freight brokers and parcel carriers sell declared value, excess value, or excess liability coverage. What they share is a mechanism: you name a dollar figure for the shipment, the carrier's exposure rises to that figure, and you pay a rate per hundred dollars of declared value. Parcel excess value tends to land in the low single dollars per hundred, with a minimum charge. Full value protection on a household move is usually quoted per thousand dollars of declared valuation, with the price moving on the deductible you accept.
None of that is insurance, and the distinction matters more than it sounds. Declared value raises a carrier's contractual liability, so you still have to show the carrier caused the loss. Cargo insurance, sold by an insurer or a licensed broker acting as an agent, pays on a covered peril whether or not anyone was negligent, which is what you want if the risk you fear is a rolled trailer, a warehouse fire, or a theft in transit. Read whether your document says liability or policy. A certificate of insurance with a named insurer and a deductible is a different animal from a tariff option, and it costs more because it covers more.
Deductibles are the quiet cost driver inside both products. A zero-deductible full value option on a valuable household shipment can run several times the price of the same valuation with a five hundred dollar deductible, and the cheapest deductible tier often sits just above the value of the single item most likely to break. Price the tiers against the specific thing you are worried about rather than against the total. That is also where inventory value caps bite: many valuation options set a per-article ceiling unless the item is separately listed and valued, which is how a listed camera body gets paid and an unlisted one does not.
Who packed the box decides who pays for what is inside it
The single most consequential term on a damage claim is usually not valuation at all, it is whether the shipment was carrier-packed or shipper-packed. Packed by owner, abbreviated PBO on a mover's inventory, shifts the presumption. If you packed the carton and the contents arrive broken while the carton itself is unmarked, the carrier's position is that the packing failed rather than the handling, and the claim narrows to visible container damage. Carrier-packed cartons reverse that. This is why professional packing, charged per carton plus materials, is best understood as buying evidence as much as buying cardboard.
The prices attach to specific tasks rather than to a vague standard of care. Expect per-carton pricing that climbs with size and fragility, a separate materials charge for dish packs, wardrobe boxes, foam and corner blocks, and a distinct crating price for anything flat, framed, stone, or glass, since a wood crate is built to dimensions and priced on labor and lumber. Palletizing, shrink wrapping and banding show up on freight shipments as their own lines. Accessorials sit alongside: liftgate service, inside delivery, long carry, limited access, residential delivery. Those are not packing, but they are the charges that keep a heavy item from being set down in a driveway and dragged.
Packaging standards give you a way to ask for something specific. Distribution-test protocols of the kind published by testing bodies for drop, compression and vibration performance are what a serious crater or fulfillment operation is working to, and asking whether an item will be packed to a drop-tested specification, double-walled, with corner protection and float inside the carton, gets a more useful answer than asking whether it will be packed well. It also tends to surface the real price of doing it properly, which is often a modest addition to an expensive shipment.
The delivery receipt, the concealed damage clock, and what a claim pays
What you write when you sign is worth real money. A clean signature on the delivery receipt or bill of lading is treated as an acknowledgment that the goods arrived in apparent good order, so inspect the outside, count the pieces, and note every crushed corner, puncture, water stain, tilted pallet and broken band on the receipt itself before the driver leaves. Photograph the item on the truck, on the ground, and again with the packaging opened but not discarded. Keep the carton, the pallet and the packing material until the claim closes, because the carrier or its adjuster has the right to inspect what failed.
Damage you find after signing is concealed damage, and it runs on a shorter and stricter clock than most customers expect: notify the carrier promptly, usually within a handful of days, and file the written claim inside the filing window stated in the contract, commonly nine months from delivery for interstate motor freight, with a separate deadline for filing suit after a claim is declined. Household goods claims often carry their own window in the mover's terms. Whatever the figure, it is in the paperwork you already have, and finding it first shapes everything else you do.
Payment itself has two settings. Actual cash value pays depreciated worth, so a nine-year-old sofa pays like a nine-year-old sofa. Replacement value, which is what full value protection is meant to deliver, gives the carrier a choice among repair, replacement with like items, or a cash settlement at current cost, and repair by the carrier's chosen restorer is a legitimate outcome rather than a dodge. Salvage is the other half: if the carrier pays replacement, it may claim the damaged item. Get a written repair estimate early, because a settlement discussion with a number in it moves faster than one without.
Priced out honestly, the protective layer on a shipment is a small fraction of what it protects. Professional packing and a sensible declared value on a single fragile, heavy, or genuinely irreplaceable item usually cost less than the deductible you would otherwise absorb, and they buy something the cheaper option cannot: a clear record of who handled what, and a paid claim that closes in weeks rather than an argument that closes in months.